
Step Two of the Replete Trading Path
Trade Nifty and Sensex with structure, not emotion.
A structured intraday option-selling framework that evaluates market conditions, refines option-leg selection, and adapts its execution approach as market behaviour evolves. Built for Nifty and Sensex traders who prioritize defined risk and disciplined execution over emotional overrides.

Why I built this basket
"Most traders don't lose because their strategy is wrong. They lose because they change the strategy mid-session based on how they're feeling. In year four, I blew ₹3.4 lakh in a single BankNifty session doing exactly that, tightening stops out of fear, then doubling size out of frustration. This basket is the opposite of that afternoon."
I've been trading live markets since 2010. This basket isn't a signal service and it isn't a set-and-forget file either. It's the intraday option-selling framework I trade myself, structured around documented execution parameters, predefined risk controls and disciplined position management.
Core Design Philosophy
That experience shaped how this execution framework was built: not around blindly following a clock, but around a structured process that evaluates changing market conditions, predefined risk parameters and disciplined execution.
Sachin Sival · Founder, Replete Equities · 16 Years Live Market Experience
The real problem with intraday option selling
Most traders don't have an edge problem. They have an execution problem.
Option selling looks simple on paper: collect theta, manage risk, square off before close. In live trading, psychology gets in the way.
Trading every move, not just high-quality setups
Most intraday option sellers struggle to sit on their hands. Every candle looks like an opportunity, so every candle becomes a trade, until the good setups get buried under the bad ones.
Changing logic based on fear or greed
A losing morning triggers tighter stops out of fear. A winning morning triggers bigger size out of greed. The rules bend to emotion instead of disciplined parameters.
Using strategies that stop working when volatility shifts
A strategy that worked in a low-volatility grind gets kept running into a high-volatility break, because nobody defined in advance when to stop using it.
No clarity on when to adjust or why
When a position moves against you, the decision to adjust, hold, or exit gets made in the moment, under pressure, with no rule written down before the trade began.
Beyond Time-Based Straddles & Strangles
A structured intraday option-selling basket, refined through execution intelligence.
Traditional intraday option selling relies on entering fixed strikes at predetermined times. Our execution framework builds upon systematic option selling by integrating volatility assessment, positioning patterns, and objective market context.
Volatility Intelligence
Market volatility can change the behaviour of option premiums. VIX-based assessment adds a volatility context to how the framework evaluates option-leg selection and position structure.
Open Interest Intelligence
Strike-level Open Interest build-ups and unwinding provide additional insight into positioning patterns and changing activity across option strikes, adding another layer of context to position selection.
VWAP-Based Market Context
Volume-Weighted Average Price provides objective market context, helping evaluate intraday trend strength and distinguishing directional momentum from mean-reverting ranges.
Multi-Layer Option-Leg Optimisation
Rather than relying on a single static indicator, multiple market inputs are evaluated together to refine option-leg selection, strike spacing, and position construction.
Fixed Time-Based Approach vs. Replete Equities Framework
Comparing conventional time-based execution with our multi-factor execution framework
Predetermined schedule based on a fixed entry time.
Evaluates prevailing market conditions and opening price discovery prior to entry.
May use fixed assumptions across differing volatility environments.
VIX-based assessment adds volatility context to option-leg and risk structuring.
Typically uses a fixed strike distance or single premium target.
Multi-factor assessment evaluating premium characteristics, delta profile, and strike positioning.
Operates with limited contextual inputs regarding broader price and positioning trends.
Integrates Open Interest distribution and VWAP context for objective market insight.
Logic may remain unchanged across shifting market regimes.
Continuously evaluated and refined across changing market cycles.
What exactly is the basket
Not a tip service. Not a buy-today-forget-tomorrow file.
It's a professionally designed intraday option selling system that focuses on selling options where probability and decay are favourable, trading with predefined rules instead of prediction, managing risk before entering trades, and squaring off positions intraday, always.
What you receive
- ✓A ready-to-import algo basket file with predefined structure
- ✓Execution logic guidelines and parameter specifications
- ✓Access to periodic framework optimisation updates
- ✓Predefined risk control rules with mandatory intraday squareoff
- ✓Usage guidelines for tracking and disciplined execution
Operating Sequence
- 1.Market Context Assessment: Evaluating opening volatility, price discovery, and index positioning prior to trade initiation.
- 2.Option-Leg Selection: Identifying strikes with favourable premium decay characteristics and defined risk parameters.
- 3.Systematic Position Entry: Executing predefined basket orders with disciplined, systematic parameters.
- 4.Risk Controls: Enforcing predefined stop-loss levels and defined downside risk boundaries.
- 5.Intraday Position Management: Intraday position management with a defined end-of-session exit process, designed to avoid planned overnight position carry.
- 6.Periodic Optimisation: Continually evaluating execution data and adapting the framework when market conditions demand it.
No prediction. No emotional overrides. Just structured, disciplined execution.
This basket is right for you if
You recognise yourself in any of these
- You've placed at least 20 live intraday option trades
- You have ₹5,00,000 or more in deployable trading capital (reference capital for the 1X complete basket)
- You prefer defined risk to aggressive speculation
- You struggle with emotional intraday decisions
- You want a structured framework instead of random trades
Not the right fit if
This basket will not work for you if you're
- ✕Guaranteed return seekers
- ✕Traders who ignore risk rules
- ✕High-frequency gamblers
- ✕Anyone unwilling to respect systematic discipline
Never traded live before? Start with the Foundation Program →
Understanding Reference Capital, Margin & Buffer
Disciplined option selling requires understanding the distinction between broker margin requirements and prudent trading capital.
₹5,00,000 Reference Capital (1X)
The recommended capital sizing to simultaneously deploy all component legs of the complete Nifty and Sensex basket.
Dynamic Exchange Margin
Actual exchange margin requirements vary across brokers, underlying index volatility, and hedge strike distances. Pure SPAN/exposure margin is lower than reference capital.
Risk & Drawdown Cushion
Capital held above pure margin provides a vital buffer to absorb intraday mark-to-market fluctuations, margin spikes during volatility expansion, and execution friction.
Continuous Evaluation & Adaptation
Continuously evaluated. Optimised when market conditions demand it.
Option selling performance depends heavily on the prevailing market regime. Volatility levels, option decay velocity, strike responsiveness, and risk characteristics all shift across market phases. A logic that performs well in one environment can encounter friction in another.
Why this framework evolves with market cycles.
Strategy configurations can evolve as structural market behaviour changes. Rather than forcing a static model onto changing markets or making arbitrary calendar tweaks, our framework is continuously evaluated against real market dynamics. When empirical data indicates a meaningful structural shift in volatility or decay behaviour, the configuration is re-optimised. Subscribers receive updates and operational guidelines according to their active access entitlement.
HISTORICAL BACKTEST BENCHMARK (ALPHA ENGINE V9)
Alpha Engine V9 — Full Multi-Index Benchmark
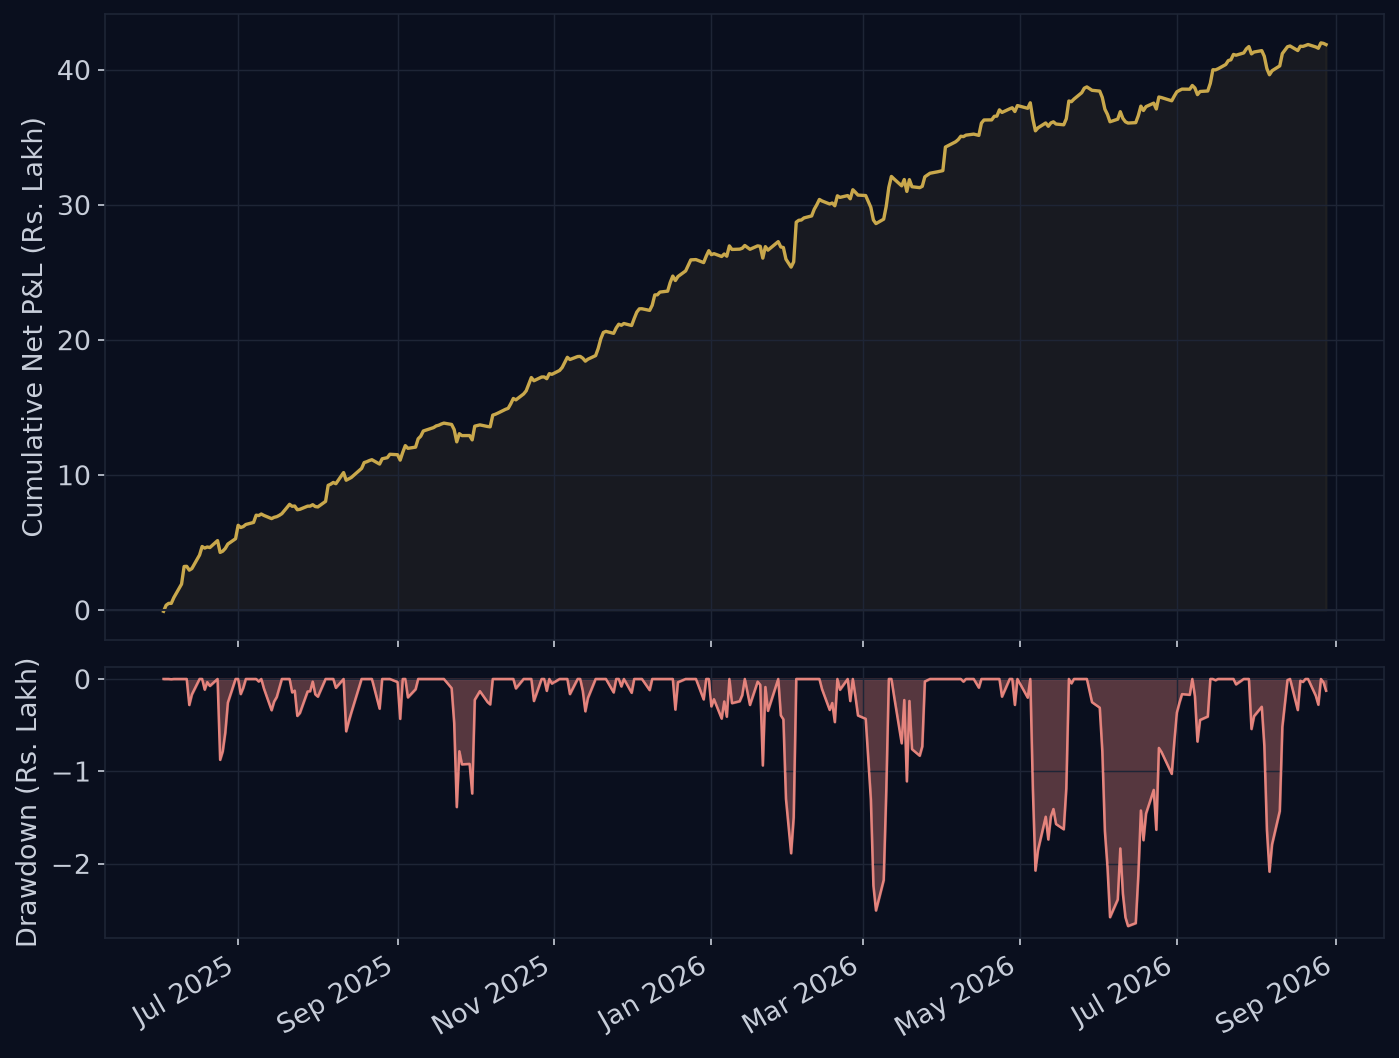
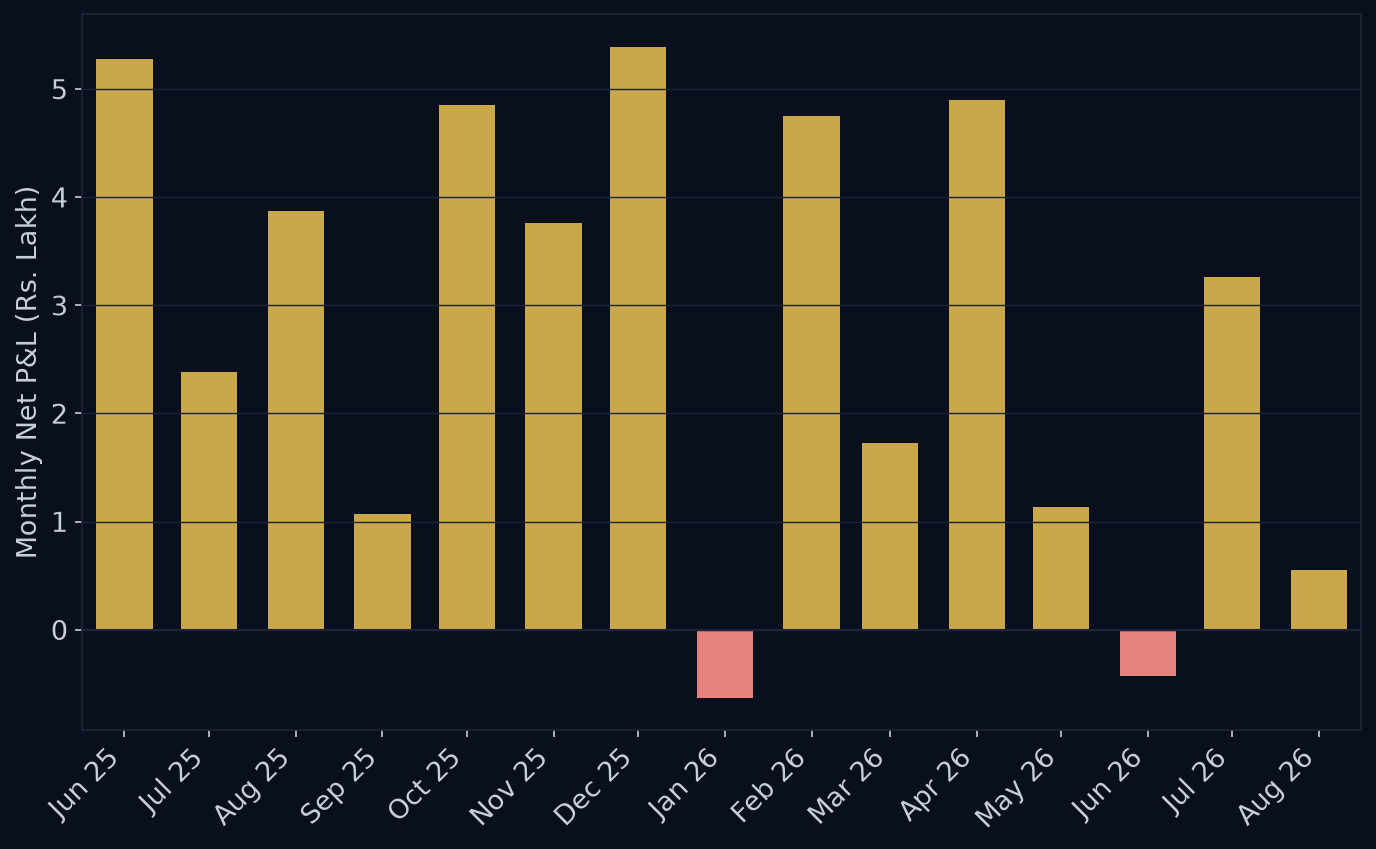
Every figure below documents the historical backtest performance of the complete Multi-Index Alpha Engine V9 portfolio across NIFTY 50 and BSE SENSEX across 15 months (310 shared trading sessions, June 2025 – August 2026). Shown net of realistic Indian F&O statutory transaction friction: flat ₹20/order brokerage, 0.1% STT on sell turnover, exchange transaction fees, 18% GST, SEBI charges, and stamp duty.
Combined equity curve & drawdown
Month-by-month net return %
Full performance breakdown
| Metric | Gross | Net |
|---|---|---|
| Total Net Profit (1X Base ₹5.0L) | ₹6.96L | ₹5.50L |
| Total Net Profit (10X Scale ₹50L) | ₹69.58L | ₹66.26L |
| Net ROI (15 Months) | 110.1% | 110.1% – 132.5% |
| Monthly average return | 7.46% | 7.46% – 8.98% |
| Annualised return (CAGR) | 89.5% | 89.5% – 107.7% |
| Profit factor | 3.48 | 3.48 – 4.45 |
| Daily win rate | 74.5% | 74.5% – 77.1% |
| Max drawdown (1X / 10X) | -₹16.65K (3.33%) | -₹1.56L (3.12%) |
| Calmar ratio (Return / MDD) | 26.88 | 26.88 – 34.56 |
| Sharpe ratio (annualised) | 6.58 | 6.58 – 7.93 |
| Profitable months (reliability) | 15 / 15 (100%) | 15 / 15 (100%) |
Champion Multi-Index Alpha Engine V9 Allocation (1X Base = ₹5.0 Lakhs): SENSEX 0DTE (2 lots), SENSEX 1DTE (1 lot), SENSEX 2DTE (2 lots), NIFTY VIX-Adaptive Short Strangle (1 lot), NIFTY Delta V2 with 0.10 Delta Hedges (1 lot), and NIFTY Prem 60 (1 lot). Scales linearly to 3X (₹15L) and 10X (₹50L). Transaction friction modelled with exact post-October 2024 SEBI/exchange statutory rates and flat ₹20/order brokerage. Backtested performance is based on historical tick data and is not a guarantee of future results; live execution may differ due to market impact and fill timing.
Capital Sizing & Brokerage Dilution Economics (1X, 3X & 10X)
Cost Drag Drops from 20.9% to 4.8%| Tier | Capital | Net P&L | Net Return | Monthly | Max DD | Sharpe | Cost Drag |
|---|---|---|---|---|---|---|---|
| 1X Base Tier (Retail) | ₹5,00,000 | +₹5.50L | +110.1% | +7.46% | 3.33% | 6.58 | 20.91% |
| 3X Growth Tier (HNI) | ₹15,00,000 | +₹19.00L | +126.7% | +8.58% | 3.17% | 7.58 | 8.96% |
| 10X Institutional Tier | ₹50,00,000 | +₹66.26L | +132.5% | +8.98% | 3.12% | 7.93 | 4.78% |
Pricing and Access Structure
Choose how many market cycles you want to trade with structure.
You're buying system access plus optimisation cycle support, not just a file.
Current Market Cycle Access
₹9,999
One-time access to the current algo basket file, ideal if you want to experience structured intraday option selling in the current market phase.
- •One-time access to the current algo basket file
- •Execution logic guidelines and parameter specifications
- •Access to the current optimisation cycle
- •One major update if released during this cycle
Instant file delivery within 5 minutes of checkout
Two Market Cycles Access
₹19,999
Designed for traders who want continuity across changing market conditions and subsequent regimes.
- •Algo Trading Tool Included — No Additional Cost
- •Current basket file and implementation guidelines
- •Next framework optimisation and cycle update
- •Coverage across two distinct market regimes
- •Priority query support during cycle transitions
Direct onboarding & payment coordination via WhatsApp
Full-Year Access
₹29,999
Best suited for serious traders who want a full-year disciplined execution framework.
- •Algo Trading Tool Included — No Additional Cost
- •Current basket file and complete documentation
- •All optimisations released over the next 12 months
- •Priority update delivery and operational guidance
- •Access to full annual cycle adaptation reviews
Priority annual onboarding via WhatsApp
Extended access plans include the supporting algo trading tool at no additional cost, so you do not need to purchase a separate third-party tool subscription for this workflow.
Current cycle basket file delivered by email within 5 minutes of payment. No onboarding call required.
How updates and access work
- •The basket file is delivered immediately after purchase
- •Extended access plans include the supporting algo trading tool at no additional cost (brokerage, exchange taxes, and VPS/API fees remain external)
- •Optimisations are released only when market structure demands it
- •There are no auto-renewals or forced subscriptions
- •After your access period ends, you may continue using the file independently
- •Future updates and execution guidance will not be included beyond your selected period
The difference is in the structure
Not all option-selling baskets are designed the same way.
You may find option-selling baskets, trading groups, or signal services available at much lower prices.
And that is completely fine.
But before comparing the price, compare what you are actually getting.
A lower-priced basket may give you access to trades. You may still need to figure out:
- •Why is this position being taken?
- •How much capital should I allocate?
- •What happens when the market moves against the position?
- •How is risk managed across multiple trades?
- •When should a position be adjusted?
- •How do different strategies work together?
- •How should performance be evaluated over an entire execution cycle?
The Replete Execution System is designed around a different approach.
Typical approach
Typical Low-Cost Basket
- –Primarily focused on trade ideas or signals
- –Strategy framework may not always be fully transparent
- –Capital allocation is often left to the subscriber
- –Risk management approach can vary
- –Focus may be on individual trades
- –Understanding the overall execution process is optional
- –Optimised primarily for low-cost access
Replete approach
Replete Execution System
- Built around structured execution
- Defined strategy framework
- Clear approach to capital allocation
- Risk management integrated into the execution process
- Designed from a portfolio and system perspective
- Helps members understand how the execution framework works
- Designed for serious participation over a complete execution cycle
The right question is not simply, “Which basket is cheaper?”
The more important question is: “What approach am I trusting with my trading capital?”
If you are simply looking for the cheapest trade calls or basket available, this may not be the right fit for you.
But if you are looking for a structured execution framework designed around defined strategies, capital allocation, risk management, and disciplined execution over a complete cycle, then the Replete Execution System is built for that purpose.
Upgrade Credit, 100% Applied
If you upgrade to the Option Strategies Mentorship Program within 60 days, 100% of the amount paid for this basket is adjusted against your mentorship fee. Your investment is never wasted, and you can move from execution to understanding to mastery smoothly.
System Logic Verification Credit
If the basket's live execution in your first trading week deviates meaningfully from its documented logic parameters, tell us and we will issue a credit toward your next access cycle. This is a system logic verification policy, not a performance guarantee. All market participation involves risk; this basket manages risk systematically, it does not remove it.
The Replete Trading Path
This is step two of a larger trading path
This basket focuses on execution discipline. Many traders later realise that consistency also requires understanding why adjustments work, managing drawdowns across cycles, position sizing across different volatility regimes, and feedback and review. For traders who want to go deeper, mentorship becomes the natural next step.
Foundations
For traders starting from zero: mechanics, risk, market structure.
Execution Systems
Rule-based intraday execution for Nifty and Sensex. This basket.
You Are HereMentorship
For traders with 3+ years live experience who want direct, 1-on-1 guidance.
Final thought
Intraday option selling doesn't need to feel chaotic.
With the right structure, discipline, and adaptation to market cycles, it can become a calm, repeatable process. This basket is built for traders who want to trade like professionals, not gamblers.
Regulatory Notice & Risk Disclaimer: All market participation involves risk of capital loss. Options trading entails substantial financial risk and is not suitable for all participants. The Replete Equities Execution System is a rule-based execution framework and analytical tool. We do not provide portfolio management services, tip services, or guaranteed returns. Past backtested performance is not a guarantee of future live execution outcomes.